How to find out if you are leaving Money on the table?
(In as little as 15 min) This free guide shows you how to review your annuity rate vs what's available NOW!
Scroll below to see what you could be missing out on with your current annuity!!!
You were sold a plan. were you sold the whole story?
Annuities can be very confusing. Surrender schedules, participation rates, index caps, rider fees...most owners can't fully explain their own contract, and most agents never sit down to walk them back through it after acquisition.
That's not your fault. But it does mean you could be leaving growth, income , or flexibility on the table now, without even knowing it.
The only way to know for sure is to look inside the contract itself...not guess, not assume, and not take the original pitch at face value!
The Four levers that make an impact on what your annuity earns Every annuity owner needs to understand, regardless of product type
The Index or Account Chosen
Your annuity's growth is based on a market index, like the S&P 500, but you're not actually buying stocks, you're watching how that index moves
The Crediting Method
There's a formula that decides how much of the index's growth you actually get to keep, and it's rarely 100%
The Crediting Period & Strategy
How often the annuity "checks in" on the market and locks in your gains can change how much money you end up with.
Renewal Rate Risk
The good rate you started with usually isn't permanent — the insurance company can lower it later, within certain limits.
"Rates are like weather...they shift, but what matters is if you're prepared for the forecast."
A lot of annuities in force today were purchased when the Federal Funds Rate was sitting near ZERO. Contract terms caps, and crediting strategies built in that environment don't automatically update just because the rate environment did
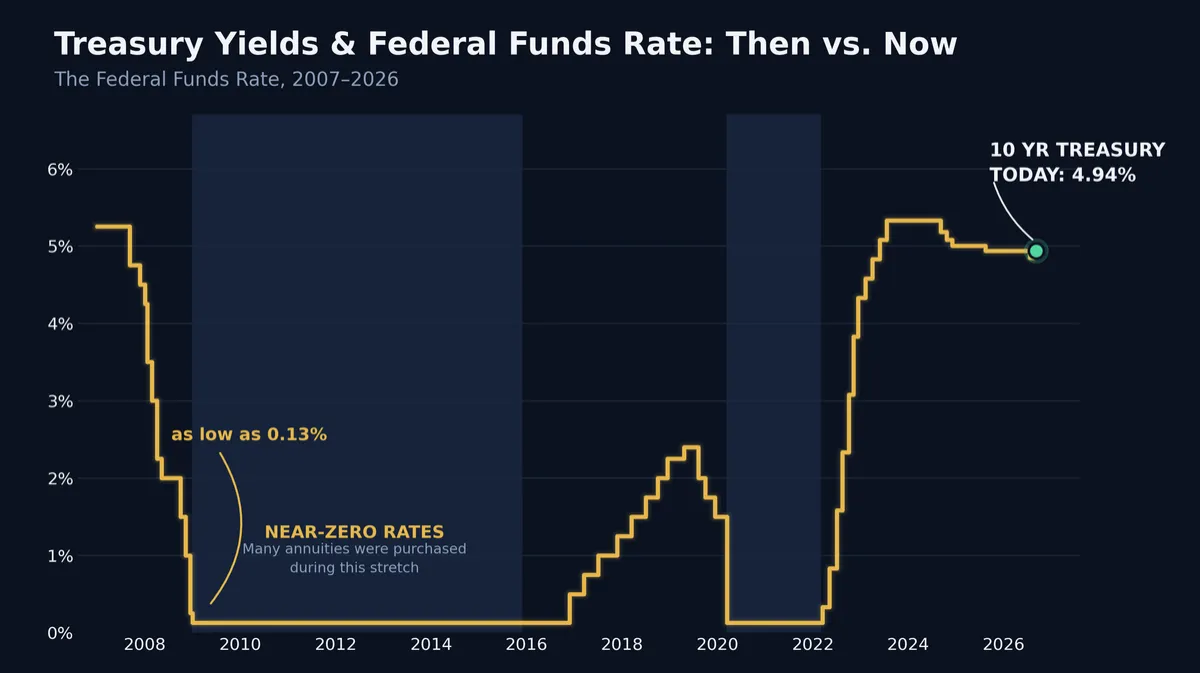
VS
This doesn't automatically mean your annuity is outdated...but it's worth checking to see if there are strategies available you might be missing out on, if you are maximizing what's available, there might be benefit in making a change. That is what The Annuity MRI is all about!
How Does the Annuity MRI Work?
#1 Performance Diagnosis
We review your most recent annual statement and measure how your annuity has performed over time
# 2 Optimization Analysis
We identify exactly where fees, caps, or outdated riders may be limiting your growth or income today.
#3 Replacement Comparison
We compare your current contract , side by side, against what's available in today's market, keeping the same goals/objective if they haven't changed.
#4 Cost-Benefit Review
We lay out the real cost of staying put next to the real costs of making a change, so the decision is based on facts, not guesswork.
#5 Action Plan
You walk away with a clear, written recommendation...keep it, adjust it, or replace it, and what each option means for you.
What do you walk away with?......Clarity Either Way!!!
MORE THAN 30,000 LIKE - MINDED PEOPLE
Before Annuity MRI
You glance at your annual statement, assume it's fine, and move on with no real way to know if that's true.
You wonder if today's annuities offer more than the one you bought years ago, but you have no way to compare.
You're not sure if surrender charges mean you're stuck, so you do nothing.
You feel like the only options are "trust your gut" or "trust a salesperson" neither feels solid.
You've heard your contract "should be fine" but nobody's ever shown you the actual numbers.
After Annuity MRI
You know exactly how your annuity has performed...and how it stacks up against what's available today
You have a clear, data-backed answer: keep it, optimize it, or consider a specific alternative.
You understand precisely what surrender charges would cost you...and whether that cost is worth it.
You've made your decision based on facts, not fear or guesswork.
You have a plan for your retirement income you feel confident about, whatever you decide to do.
Before You Get Started....
Does this cost anything?
No. The Annuity MRI guide and review are completely free, with no obligation to move your money or work with me afterward.
What do I receive right away?
Your free copy of The Annuity MRI guide, delivered straight to your inbox. Work through it yourself, or bring it to a free call with me if you'd rather walk through it together.
What do I need to provide for the Annuity MRI?
Just your most recent annuity statement or contract, if you have it. If you don't have it handy, we can still walk through what you remember and track it down together.
What if I actually like my annuity?
If we can leave with confirmation that it's working the way it should, then you have the peace of mind about money you've already committed is worth something too. If we can't confirm its working the way it should, we can show you what options you have.
Am I obligated to purchase anything?
No. You get a written diagnosis either way. If a change makes sense, I'll show you exactly why. If it doesn't, I'll tell you that too
How long does the process take?
About 15 minutes to gather your information, then a short call together to walk through what we found.
This material is for educational purposes and is not a guarantee of any specific outcome. Annuity guarantees are backed by the financial strength of the issuing insurance carrier. Consult your contract and a licensed professional before making any changes to an existing annuity.
Solid Ground Financial LLC. 2026 All Rights Reserved-3030 N Rocky Point Dr W, Ste 150A, Tampa, FL 33607-5803
Terms and Conditions - Privacy Policy
his is a Paragraph Font